Federal Reserve Interest Rate Decision: Inflation at 3.2% in January 2026
Ads
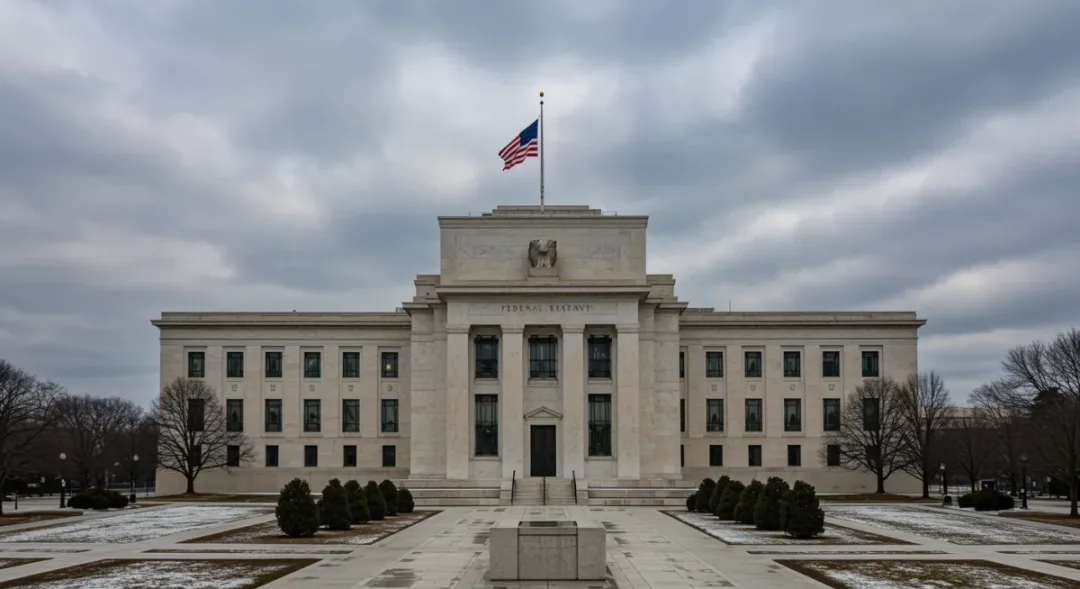
The Federal Reserve announced its latest interest rate decision on Wednesday, January 15, 2026, choosing to maintain the benchmark rate amid ongoing economic uncertainty. As inflation data revealed a reading of 3.2% for January, policymakers faced mounting pressure to balance growth objectives with price stability. This decision marks a critical juncture for the American economy, potentially shaping consumer finances, investment strategies, and broader market trajectories throughout the year.
Ads
The Federal Reserve’s Decision Explained
After a two-day policy meeting, the Federal Open Market Committee voted to keep the federal funds rate unchanged at its current level. This decision surprised some analysts who had anticipated a potential adjustment given the persistent inflation environment. The central bank’s choice reflects a nuanced assessment of economic conditions, acknowledging both progress in bringing inflation down and remaining risks that could reverse those gains.
Ads
Federal Reserve Chair addressed reporters during the post-meeting press conference, emphasizing that the decision was not a signal of complacency but rather a recognition that the current policy stance remains appropriate. The Chair noted that while inflation has cooled significantly from its peak levels, the 3.2% reading still exceeds the Fed’s long-term target of 2%, necessitating continued vigilance.

Key Factors Driving the Decision
- January inflation data came in at 3.2%, above market expectations
- Labor market conditions remain resilient with unemployment holding steady
- Consumer spending shows mixed signals heading into 2026
- Global economic uncertainties continue to cloud the outlook
The decision to hold rates steady suggests that Fed officials believe the current restrictive monetary policy is working as intended. By keeping borrowing costs elevated, the central bank aims to gradually bring inflation back to target without triggering a recession. However, this approach places continued pressure on households and businesses that rely on credit.
Understanding the 3.2% Inflation Reading
The January 2026 inflation figure of 3.2% represents a complex picture for policymakers. On one hand, this marks substantial progress from the 9.1% peak reached in 2022, demonstrating that the Fed’s aggressive rate hiking campaign has succeeded in cooling price pressures. On the other hand, the fact that inflation remains well above the 2% target creates a dilemma for officials who must decide how long to maintain restrictive policy.
Economists have been closely monitoring the components of the inflation gauge, looking for evidence that price pressures are becoming more broad-based rather than concentrated in specific sectors. The January data showed mixed signals, with services inflation remaining sticky while goods prices continued to moderate. This divergence complicates the Fed’s task, as different sectors respond to monetary policy at different speeds.
Inflation Breakdown by Category
- Housing costs increased 4.1%, remaining a major driver of overall inflation
- Food prices rose 2.8%, showing moderation from previous months
- Energy costs declined 1.2%, providing some downward pressure
- Core inflation, excluding food and energy, held at 3.4%
The persistence of shelter costs in particular has frustrated policymakers, as this category tends to show the slowest response to interest rate changes. Many economists believe that shelter inflation will continue to moderate throughout 2026 as new housing supply comes online and mortgage rates encourage more rental activity.
Market Reactions to the Fed’s Decision
Financial markets responded with relative calm to the Fed’s decision, interpreting the hold as a signal that the central bank is taking a patient approach rather than pivoting prematurely. Stock indices fluctuated in the hours following the announcement before settling into modest gains. Bond yields dipped slightly, reflecting expectations that rates will remain higher for longer.
Currency markets showed limited movement, with the dollar index remaining essentially flat against a basket of trading partners. This suggests that market participants had already priced in the likelihood of a hold decision, with the real focus shifting to the Fed’s forward guidance about future policy moves.
Individual investor sentiment appears mixed, with some viewing the decision as a vote of confidence in the economy while others worry that persistently high rates could weigh on corporate earnings. The technology sector, which has been particularly sensitive to interest rate movements, showed modest gains following the announcement.
Sector Performance Post-Announcement
- Financial services stocks rose 0.8% on expectations of continued net interest margin compression
- Technology stocks gained 0.5% as rate-sensitive sectors breathed a sigh of relief
- Real estate investment trusts declined 1.2% amid ongoing rate headwinds
- Utilities and consumer staples showed defensive strength, up 0.3% and 0.4% respectively
Market analysts widely expect that volatility will increase in the coming months as investors digest incoming economic data and assess the likelihood of future rate adjustments. The Fed’s communication strategy will be crucial in managing expectations and avoiding market disruptions.
Impact on American Consumers
For everyday Americans, the Fed’s decision to hold rates steady means that borrowing costs will remain elevated for the foreseeable future. Homebuyers continue to face mortgage rates hovering around 6.5%, making housing affordability a challenge for many prospective purchasers. Credit card rates remain near historic highs, encouraging consumers to pay down balances or reduce spending.
Savings accounts, however, continue to benefit from the higher rate environment, with many banks offering yields above 4.5% on deposits. This has encouraged some households to increase their savings rate, building a financial cushion amid economic uncertainty. For retirees and those living on fixed incomes, the higher yields have provided some relief from inflation’s erosive effects.
Consumer Financial Implications
- 30-year fixed mortgage rates remain around 6.5%, limiting housing market activity
- Credit card annual percentage rates average 20-24%, encouraging debt reduction
- High-yield savings accounts offer 4.5-5.0% APY on deposits
- Auto loan rates stay elevated at 7-9% for new vehicle purchases
Consumer confidence indices have shown resilience despite the higher cost of borrowing, suggesting that Americans are adapting to the new rate environment. However, economists warn that prolonged high rates could eventually weigh on consumer spending, which accounts for roughly 70% of economic activity.
What Economists Are Saying
Economists and financial analysts have offered varied interpretations of the Fed’s decision, with some praising the patience demonstrated by policymakers while others worry about the risks of waiting too long to adjust policy. The consensus view seems to be that the Fed is navigating a delicate balancing act, attempting to bring inflation down without triggering an economic downturn.
Many private sector economists have revised their forecasts to reflect the likelihood of rates remaining higher for longer than previously anticipated. Several major financial institutions now expect the Fed to hold steady through at least the first half of 2026, with potential rate cuts possible in the latter half of the year if inflation continues to moderate.
Analyst Forecasts for 2026
- Goldman Sachs projects one rate cut by Q3 2026 if inflation falls below 2.5%
- JPMorgan economists expect rates to remain unchanged through the full year
- Bank of America analysts see potential for two rate cuts in late 2026
- Morgan Stanley strategists emphasize data dependency as key to future decisions
The divergence in forecasts highlights the uncertainty surrounding the economic outlook. Factors ranging from geopolitical tensions to shifts in consumer behavior could significantly impact the trajectory of inflation and, consequently, Fed policy. Market participants are advised to maintain flexibility and monitor incoming data closely.
Looking Ahead: What to Watch
As the year progresses, several key indicators will influence the Fed’s thinking on interest rate policy. Monthly inflation reports will be scrutinized for evidence that price pressures are continuing to ease toward the 2% target. Labor market data will help policymakers assess the sustainability of current economic growth.
Central bank officials have emphasized that their decisions will remain data-dependent, avoiding any pre-commitment to a particular policy path. This approach allows the Fed to respond to evolving economic conditions while maintaining credibility with markets. However, it also means that uncertainty will persist, potentially affecting business investment and hiring decisions.
Key Economic Releases to Monitor
- Monthly Consumer Price Index reports due on the 12th of each month
- Quarterly GDP growth estimates released by the Bureau of Economic Analysis
- Monthly employment situation reports from the Bureau of Labor Statistics
- Consumer confidence indices from the Conference Board and University of Michigan
The Fed’s next policy meeting is scheduled for late March 2026, with markets expecting another hold decision unless economic data surprises significantly in either direction. Investors and policymakers alike will be watching closely for any signs that the economic landscape is shifting in ways that might require a policy response.
| Key Point | Brief Description |
|---|---|
| Fed Holds Rates Steady | The Federal Reserve maintains benchmark interest rates unchanged in January 2026 decision |
| Inflation at 3.2% | January inflation reading remains above Fed’s 2% target, signaling continued vigilance needed |
| Market Reaction | Financial markets respond calmly, with stocks showing modest gains and bond yields dipping slightly |
| Consumer Impact | Borrowing costs remain elevated with mortgage rates around 6.5% and credit card rates at 20-24% |
Frequently Asked Questions
Why did the Federal Reserve keep interest rates unchanged in January 2026?▼The Fed chose to hold rates steady because inflation at 3.2% remains above its 2% target, and officials want to ensure price pressures continue to ease before adjusting policy. The decision reflects a cautious approach to avoid premature easing that could allow inflation to resurge.
How does the 3.2% inflation rate affect mortgage rates?▼While mortgage rates are influenced by multiple factors including Treasury yields and lender competition, the Fed’s policy decisions indirectly affect mortgage rates. With rates held steady, mortgage rates remain around 6.5%, keeping housing affordability challenging for many prospective homebuyers.
When might the Federal Reserve consider cutting interest rates?▼Most economists expect the Fed to maintain its wait-and-see approach, potentially considering rate cuts later in 2026 if inflation consistently falls toward 2.5% or lower. The Fed has emphasized that future decisions will remain data-dependent, avoiding any pre-commitment to a specific timeline.
How does the Fed’s decision impact savers and investors?▼Savers continue to benefit from high-yield savings accounts offering 4.5-5.0% APY, while investors face a challenging environment with elevated borrowing costs affecting corporate earnings and valuations. The decision creates a mixed outlook for different segments of the population.
What economic indicators should Americans watch going forward?▼Key indicators to monitor include monthly CPI reports, quarterly GDP growth, employment situation reports, and consumer confidence indices. These data points will help shape expectations for future Fed policy decisions and provide insight into the overall health of the economy.
Conclusion
The Federal Reserve’s decision to maintain interest rates at their current level, against the backdrop of 3.2% inflation in January 2026, underscores the delicate balance policymakers face in guiding the economy. While significant progress has been made in bringing inflation down from its peak, the journey toward the 2% target remains incomplete. Americans should prepare for a period of continued elevated borrowing costs while staying informed about economic developments that could shape future policy directions. The Fed’s patient approach reflects a commitment to achieving sustainable price stability without unnecessarily risking economic growth, though the ultimate success of this strategy will depend on evolving economic conditions in the months ahead.
Written by
Rita Luiza
Rita Luiza writes about news for insider.onlyshein.com. Each article explains how things work, compares published details such as prices, policies and program rules, and points readers to the official source before they decide.