Home Equity Strategies: Using Built-Up Value for Renovations Without Refinancing
Ads
Homeowners can access their property’s built-up equity for renovations through home equity loans, HELOCs, and other financing options that avoid refinancing while preserving favorable mortgage rates.
Ads
Your home likely represents your most significant financial asset, and over time, as you pay down your mortgage and property values rise, you accumulate substantial equity. This built-up value presents a powerful opportunity to fund major renovations without the hassle of refinancing your existing mortgage. Understanding home equity strategies allows you to make informed decisions about how to finance your next home improvement project while maintaining the benefits of your current loan terms.
Ads
Understanding Home Equity and How It Works
Home equity represents the portion of your property that you actually own, calculated by subtracting your remaining mortgage balance from your home’s current market value. For example, if your home is worth $400,000 and you owe $250,000 on your mortgage, you have $150,000 in equity. This equity grows as you make monthly payments and as market conditions increase your property’s value. Understanding this dynamic is essential for homeowners considering renovation financing options.
The amount of equity you can access typically depends on your loan-to-value ratio, which lenders usually cap around 80 to 85 percent. This means most financial institutions will allow you to borrow up to that threshold minus your existing mortgage balance. Before pursuing any home equity strategy, request a professional appraisal to determine your property’s current market value accurately. This step ensures you have realistic expectations about how much funding you can secure.
Factors That Influence Your Available Equity
- Current market conditions in your neighborhood
- Your original down payment and mortgage terms
- Payment history and how much principal you’ve paid
- Any changes you’ve made that increase property value
Many homeowners underestimate their equity because they focus only on what they originally paid rather than current market conditions. Consulting with a local real estate agent or using online valuation tools provides a clearer picture of your available funds. This knowledge empowers you to explore various financing routes with confidence.
Home Equity Loans vs. HELOCs: Key Differences
Two primary options exist for accessing your home equity without refinancing: home equity loans and home equity lines of credit, commonly known as HELOCs. Each functions differently and suits distinct financial situations. Home equity loans provide a lump sum with fixed interest rates and predictable monthly payments, making them ideal for planned renovation projects with known costs. HELOCs function more like credit cards, offering a revolving credit line you can draw from as needed during a draw period, typically with variable interest rates.

The choice between these options depends on your comfort level with variable rates, your need for flexibility, and how quickly you plan to complete renovations. A home equity loan might make more sense if you prefer knowing exactly what you’ll pay each month and want to complete your project in one phase. Conversely, a HELOC works well if you prefer drawing funds as needed, particularly for longer renovation timelines or if unexpected expenses arise during the process.
Comparing Loan Structures
- Home equity loans offer fixed rates and single disbursements
- HELOCs provide flexibility with variable rates and ongoing access
- Home equity loans typically have higher closing costs upfront
- HELOCs often have lower initial costs but rate adjustment risks
Consider speaking with multiple lenders to compare terms, as interest rates and fee structures vary significantly. Some institutions offer promotional rates for HELOCs that make them initially attractive, though understanding the long-term rate adjustment mechanism is crucial for accurate budgeting.
Cash-Out Refinancing Alternatives Worth Exploring
While cash-out refinancing remains a popular option, many homeowners overlook alternatives that preserve their existing mortgage’s favorable interest rate. If you secured your mortgage when rates were low, refinancing would mean giving up that advantage. Home equity strategies allow you to access funds while keeping your original mortgage intact, which often proves financially smarter when current rates are higher than your existing loan.
Piggyback financing represents another alternative where you take out a second mortgage alongside your primary loan, potentially avoiding private mortgage insurance. This approach works particularly well for homeowners who made smaller down payments initially and have since built significant equity. Additionally, some lenders offer renovation-specific loans that incorporate the projected value of improvements into the lending criteria, potentially allowing you to borrow more than your current equity supports.
When to Consider Alternative Financing
- Your current mortgage rate is significantly lower than market rates
- You plan to sell within a few years and want minimal closing costs
- You want to preserve your existing mortgage terms
- You need funds quickly without a full refinancing process
Weighing these alternatives against traditional refinancing requires careful analysis of your long-term financial goals, current equity position, and how long you intend to remain in the home. A financial advisor can help model different scenarios to determine which approach maximizes your benefits.
Strategic Renovation Planning with Equity
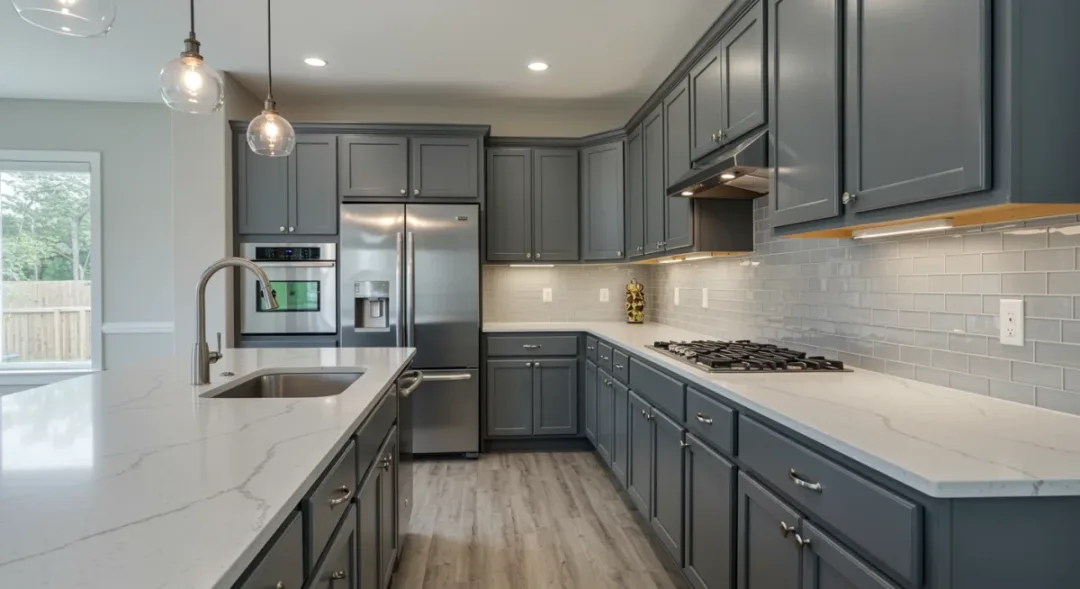
Not all renovations yield equal returns on investment, making strategic planning essential when using home equity for improvements. Focus on projects that increase your property’s value while enhancing your daily living experience. Kitchen and bathroom updates consistently rank among the highest-return renovations, offering strong appeal to future buyers while providing immediate enjoyment for current residents.
Energy-efficient improvements deserve particular attention because they reduce ongoing costs while increasingly appealing to environmentally conscious buyers. Replacing windows, upgrading insulation, installing solar panels, or switching to energy-efficient HVAC systems can qualify for additional financing incentives in some cases. These improvements often pay for themselves through utility savings, effectively using your equity to generate ongoing returns rather than one-time value increases.
High-Value Renovation Projects
- Kitchen remodels with updated appliances and countertops
- Bathroom updates including modern fixtures and layouts
- Adding usable square footage through room conversions
- Curb appeal improvements like siding and landscaping
Creating a detailed scope of work with cost estimates before accessing your equity helps ensure you borrow appropriately. Over-borrowing ties up equity unnecessarily, while under-borrowing can leave projects incomplete. Building in a contingency buffer of 10 to 20 percent accounts for unexpected expenses that commonly arise during renovation projects.
Risks and Important Considerations
Using your home as collateral carries inherent risks that require careful evaluation. Your home secures the loan, meaning failure to repay could result in foreclosure. Before proceeding, honestly assess your ability to handle additional monthly payments alongside your existing mortgage. Calculate the total debt burden and ensure sufficient income stability supports the obligation.
Market conditions can affect your equity position, and economic downturns might reduce your property’s value while you carry the renovation debt. Maintaining a financial buffer protects against unexpected job loss or income reduction. Some homeowners opt for shorter loan terms to pay off equity faster, while others prefer longer terms for lower monthly payments, accepting higher total interest costs for increased cash flow flexibility.
Protecting Your Financial Position
- Maintain emergency savings separate from renovation funds
- Consider the impact on your debt-to-income ratio
- Review your job security and income stability
- Understand all fees and closing costs associated with equity access
Reading the fine print regarding prepayment penalties, rate adjustment mechanisms, and draw period terms prevents unpleasant surprises later. Some HELOCs, for instance, convert to repayment terms that significantly increase monthly payments when the draw period ends, requiring careful planning for this transition.
Making the Right Financial Decision
Choosing the best home equity strategy ultimately depends on your unique circumstances, financial goals, and comfort with risk. Take time to gather all relevant information, compare multiple lender offers, and honestly evaluate your ability to manage additional debt. The right choice aligns with your long-term financial plan while providing the funds needed to improve your home.
Consider working with a financial planner or mortgage advisor who can provide personalized guidance based on your complete financial picture. They can help you understand how different options affect your overall financial health, retirement planning, and estate considerations. Making informed decisions about your home equity protects your most valuable asset while achieving your renovation goals.
Conclusion
Home equity strategies offer viable pathways to fund renovations without refinancing, allowing homeowners to leverage built-up value while preserving advantageous mortgage terms. By understanding the differences between home equity loans and HELOCs, evaluating alternatives, and carefully planning renovations, you can make informed decisions that enhance your property and financial security. Take time to assess your options thoroughly, compare terms across lenders, and choose the approach that best matches your goals and risk tolerance.
| Key Point | Brief Description |
|---|---|
| Home Equity Loans | Lump sum financing with fixed rates and predictable monthly payments for planned projects. |
| HELOCs | Revolving credit line with variable rates offering flexibility during renovation timelines. |
| Preserving Low Rates | Access equity without giving up favorable mortgage terms from previous years. |
| Strategic Renovations | Focus on kitchen, bathroom, and energy-efficient improvements for best returns. |
Frequently Asked Questions
What is the main difference between a home equity loan and a HELOC?▼A home equity loan provides a one-time lump sum with a fixed interest rate and consistent monthly payments, while a HELOC works like a credit card with a revolving credit line, typically featuring variable rates and flexibility to draw funds as needed during the draw period.
How much of my home equity can I actually borrow?▼Most lenders allow you to borrow up to 80-85% of your home’s value minus your existing mortgage balance. Your credit score, income, and debt-to-income ratio also influence the amount a lender will approve, so getting pre-qualified helps set realistic expectations.
Why should I use home equity instead of refinancing my mortgage?▼If you have a low interest rate on your current mortgage, refinancing would mean losing that rate and potentially paying higher costs. Home equity strategies let you access funds while keeping your existing mortgage intact, preserving favorable terms and avoiding a full refinancing process.
What renovations offer the best return on home equity investment?▼Kitchen and bathroom remodels consistently provide the highest returns, followed by adding usable square footage, improving curb appeal, and making energy-efficient upgrades. Focus on improvements that appeal to future buyers while enhancing your current living experience.
What risks should I consider before using home equity for renovations?▼Since your home serves as collateral, defaulting on payments could lead to foreclosure. Consider your job security, maintain emergency savings, and ensure you can comfortably handle additional monthly payments. Review all terms carefully, including potential rate adjustments and prepayment penalties.
Conclusion
Home equity strategies offer homeowners powerful ways to fund renovations without refinancing, preserving beneficial mortgage terms while accessing needed capital. Whether choosing a home equity loan or HELOC, understanding your options, planning strategically, and carefully evaluating risks leads to sound financial decisions. Your home’s built-up value represents a significant resource—use it wisely to enhance your property and financial future.
Written by
Lucas Bastos
Lucas Bastos writes about home for insider.onlyshein.com. Each article explains how things work, compares published details such as prices, policies and program rules, and points readers to the official source before they decide.